The Appraiser Is Coming: What Happens Next & How to Handle an Appraisal Rebuttal
Learn what happens when the appraiser visits your home, how an appraisal gap works, and the step-by-step appraisal rebuttal process if value comes in low.
Going under contract is a major milestone in any real estate transaction, but before closing day arrives, one critical checkpoint remains: the home appraisal.
When the lender orders the appraisal, sellers and buyers often wonder what to expect during the visit, what happens if the report comes in below the agreed purchase price, and how to successfully challenge a low valuation. Here is your complete guide to navigating the entire appraisal timeline — from walk-through to closing.
1. What Is a Home Appraisal?
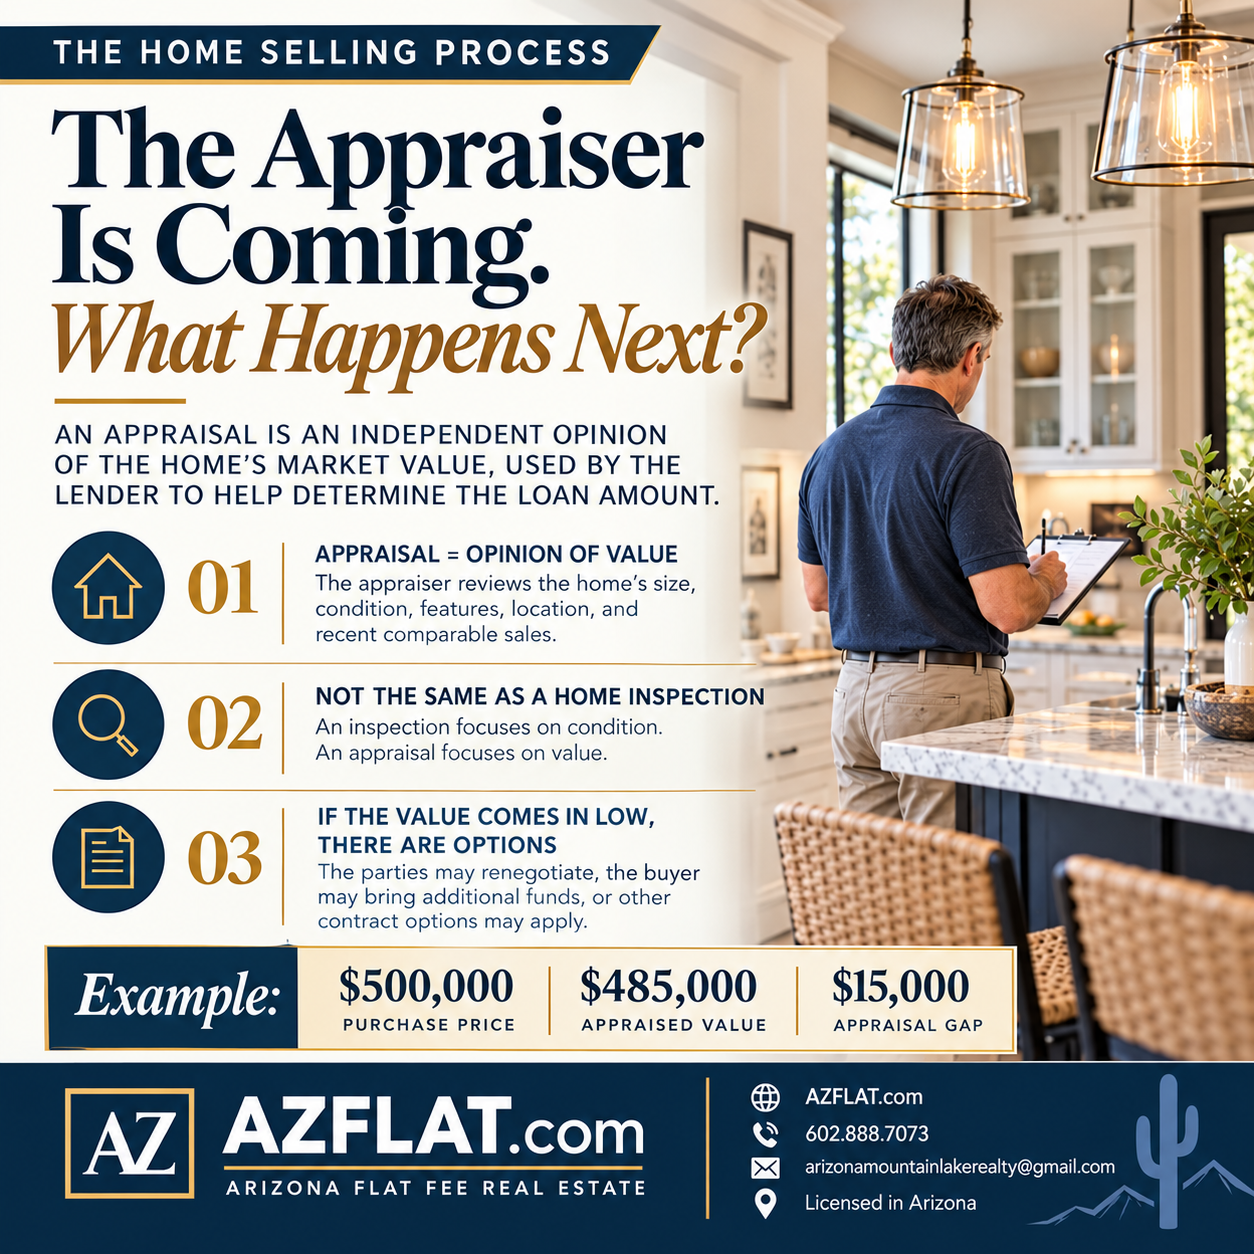
A home appraisal is an unbiased, professional opinion of a home's fair market value.
When a buyer secures financing, the lender requires an independent appraisal to ensure the collateral — the home — is worth at least the agreed purchase price before funding the loan.
During an on-site visit, the certified appraiser evaluates key elements of the property:
- Total living area: Heated and cooled square footage, room count, and floor plan flow.
- Overall condition: Age, wear and tear, updates, and major systems (roof, HVAC, plumbing, electrical).
- Special features and amenities: Pools, covered patios, high-end remodels, or energy-efficient installations.
- Location and neighborhood factors: School boundaries, proximity to busy roads, and local market trends.
- Comparable closed sales ("Comps"): Recent sales of similar homes within the immediate radius — typically within 0.5 to 1 mile, closed within the past 3 to 6 months.
The appraiser does not determine what a buyer is willing to pay. They determine what the market data supports as a reasonable value for the property. That distinction matters enormously when a gap appears between the contract price and the appraised value.
2. Appraisal vs. Home Inspection: Knowing the Difference
Many first-time sellers and buyers confuse these two milestones, but they serve two distinct purposes.
| Feature | Home Inspection | Home Appraisal |
|---|---|---|
| Primary Goal | Evaluates physical condition and safety | Determines fair market value |
| Who Orders It? | The buyer (optional but highly recommended) | The buyer's mortgage lender (mandatory for loans) |
| Focus Areas | Foundation, roof, plumbing, leaks, code violations, structural defects | Comparable sales, square footage, neighborhood trends, property features |
| Outcome | Repair requests or credit negotiations | Loan approval, appraisal gap, or renegotiation |
A home inspection focuses on condition. An appraisal focuses on value. Both can affect the final terms of a transaction, but they operate independently and are ordered by different parties for different reasons.
3. What Happens During the Appraiser's Visit?
The appraiser's on-site visit typically lasts between 30 minutes and two hours depending on the size and complexity of the property. Here is what to expect:
Before the visit: Your listing agent should provide the appraiser with a packet that includes a list of recent improvements, dates completed, dollar amounts invested, and a copy of the survey or floor plan. This is not an attempt to influence the appraiser — it is simply providing accurate information that helps them do their job correctly.
During the visit: The appraiser will measure the exterior of the home, walk through every room, note the condition of major systems, photograph the property inside and out, and document any features that add or detract from value. Make sure all areas of the home are accessible, including the attic, electrical panel, and any crawlspaces.
After the visit: The appraiser returns to their office, selects comparable sales, makes adjustments for differences between the subject property and each comp, and produces a written report — typically delivered to the lender within 3 to 10 business days.
4. Understanding the Appraisal Gap
If the appraiser values the property at or above the contracted purchase price, the loan underwriting proceeds smoothly. However, if the value comes in below the contract price, an appraisal gap occurs.
Real-World Example:
- Agreed Purchase Price: $500,000
- Appraised Value: $485,000
- Appraisal Gap: $15,000
Because mortgage lenders only base the loan-to-value (LTV) ratio on the appraised amount, the remaining $15,000 difference must be resolved before the loan can fund. Common ways parties handle an appraisal gap include:
- The seller reduces the price: Lowering the sales price to match the $485,000 valuation eliminates the gap entirely.
- The buyer brings cash: The buyer pays the $15,000 gap out of pocket on top of their original down payment.
- Meeting in the middle: Buyer and seller split the difference — for example, the seller drops $7,500 and the buyer covers the remaining $7,500.
- Exercising the appraisal contingency: If negotiations stall, standard Arizona purchase contracts allow the buyer to cancel and recover their earnest money deposit.
- Filing an appraisal rebuttal: If there are clear errors or overlooked market data in the report, the parties can formally dispute the valuation.
Which path makes sense depends on the strength of the market, the buyer's financial position, and whether the appraisal report itself contains defensible errors.
5. The Appraisal Rebuttal Process (Reconsideration of Value)
If you and your agent believe the appraisal report contains factual mistakes or failed to use accurate comparable sales, you can request a Reconsideration of Value (ROV).
An appraisal rebuttal is not an argument over opinion. It requires verifiable evidence and follows a strict legal and professional protocol under federal Appraiser Independence Requirements (AIR) established by Dodd-Frank.
Step 1: Review the Full Report for Material Errors
Obtain a copy of the appraisal from the lender and audit it line by line. Look for objective, factual inaccuracies such as:
- Incorrect square footage, room count, or bathroom counts
- Failure to credit major upgrades (renovated kitchen, new roof, pool, solar panels)
- Rating property condition as "fair" when full renovations took place
- Misidentifying the property subdivision, zoning, or school district boundaries
- Using comparable sales from across major dividing lines such as highways or different school zones
Even a single factual error — like crediting 1,800 square feet when the home is actually 2,050 square feet — can meaningfully affect the final valuation.
Step 2: Identify Better Comparable Sales
The core of any appraisal lies in the comps. If the appraiser selected inferior properties or used distressed sales such as short sales or foreclosures, work with your real estate agent to locate 3 to 5 superior comps. Valid comparable properties must:
- Be closer in physical proximity to the subject home
- Have closed more recently (within the last 90 to 180 days)
- Feature similar gross living area (GLA), age, lot size, and finish quality
Your agent has access to the same MLS data the appraiser used. If better comps exist and were not considered, that is a legitimate basis for a rebuttal.
Step 3: Complete the Lender's ROV Package
Under federal appraisal independence requirements, neither the agent, buyer, nor seller may directly contact or pressure the appraiser. All communication must flow through the lender.
Your agent works with the buyer's loan officer to obtain the lender's specific Reconsideration of Value form. The rebuttal package should include:
- A concise, fact-based summary documenting the discrepancies
- Side-by-side comp matrices showing the appraiser's comps versus your proposed comps
- Permits, receipts, or photos documenting upgrades the appraiser failed to credit
- Any factual corrections to the report's property data
Keep the tone professional and data-driven. Appraisers respond to evidence, not emotion.
Step 4: Appraiser Review and Determination
The mortgage underwriter forwards the formal rebuttal packet to the appraisal management company (AMC) or the original appraiser. The appraiser will either:
- Accept and adjust: Revise the valuation upward based on the new information.
- Stand by the value: Provide written justification explaining why the new comps or arguments did not warrant a change.
If the rebuttal is denied and the report clearly shows gross negligence or a pattern of errors, the buyer's lender may evaluate whether their guidelines allow ordering a second, independent appraisal.
6. Best Practices to Prepare Before the Appraiser Arrives
Preventing a low appraisal is far easier than fighting one. Before the appraiser visits:
Compile an Appraiser Packet. Prepare a folder on the kitchen island with a list of recent improvements, dates completed, dollar amounts invested, and a copy of the survey or floor plan. Appraisers appreciate organized documentation — it reduces the chance they overlook something.
Showcase Recent Comps. Have your listing agent provide recent neighborhood sales that justify the contract price. The appraiser is not obligated to use them, but they are required to consider them.
Maximize Curb Appeal and Access. Clear paths to the attic, electrical panel, and crawlspaces. Ensure all interior and exterior lights operate properly. A home that presents well and is easy to inspect signals a well-maintained property.
Be Present but Not Intrusive. The seller or listing agent may be present during the visit to answer questions and point out upgrades. Do not follow the appraiser from room to room or attempt to influence their observations — simply be available if they have questions.
7. What Happens If the Appraisal Comes In Low and the Deal Falls Apart?
If the appraisal gap cannot be resolved through negotiation or a successful rebuttal, and the buyer exercises their appraisal contingency, the transaction terminates. The buyer typically recovers their earnest money deposit, and the property goes back on the market.
For sellers, this is a signal to reassess pricing strategy. A low appraisal on a relisted property can affect future negotiations, since the report may be referenced by subsequent buyers' lenders. Working with an experienced agent to price the property accurately from the start — and to prepare a strong appraiser packet — is the most effective way to avoid this outcome.
8. How Flat-Fee Sellers Navigate Appraisals
Sellers who list through a flat-fee MLS service like Dash List by Mountain Lake Realty have the same appraisal process as any other transaction. The appraisal is ordered by the buyer's lender, not the listing agent, so the listing structure has no bearing on the appraisal outcome.
What does matter is having an experienced, licensed Arizona broker in your corner who can:
- Help you price the property accurately using current market data
- Prepare a professional appraiser packet before the visit
- Identify errors in the appraisal report
- Source superior comparable sales for a rebuttal
- Negotiate the appraisal gap on your behalf
At Dash List, our low flat-fee listing commission means you keep more of your equity — and our full-service support means you are never navigating the appraisal process alone.
Learn more about our pricing and packages, or use our savings calculator to see how much you could save compared to a traditional 3% listing commission.
Dash List by Mountain Lake Realty
Sell smarter. Keep more equity.
Arizona sellers choose Dash List for full-service MLS representation at a low flat-fee listing commission — starting at $59 upfront plus 0.5% at closing.
☎ (602) 881-8674 | 🌐 azflat.com | Licensed in Arizona — Thomas Mastromatto, Broker #BR104207000
Explore Topics
Written by
Thomas Mastromatto
Content creator and writer sharing insights and stories.