$10,000 Off the Price vs. $10,000 Toward Closing Costs
A $10,000 seller concession sounds the same either way — but it can affect your Arizona home purchase very differently. Here is what buyers need to know.
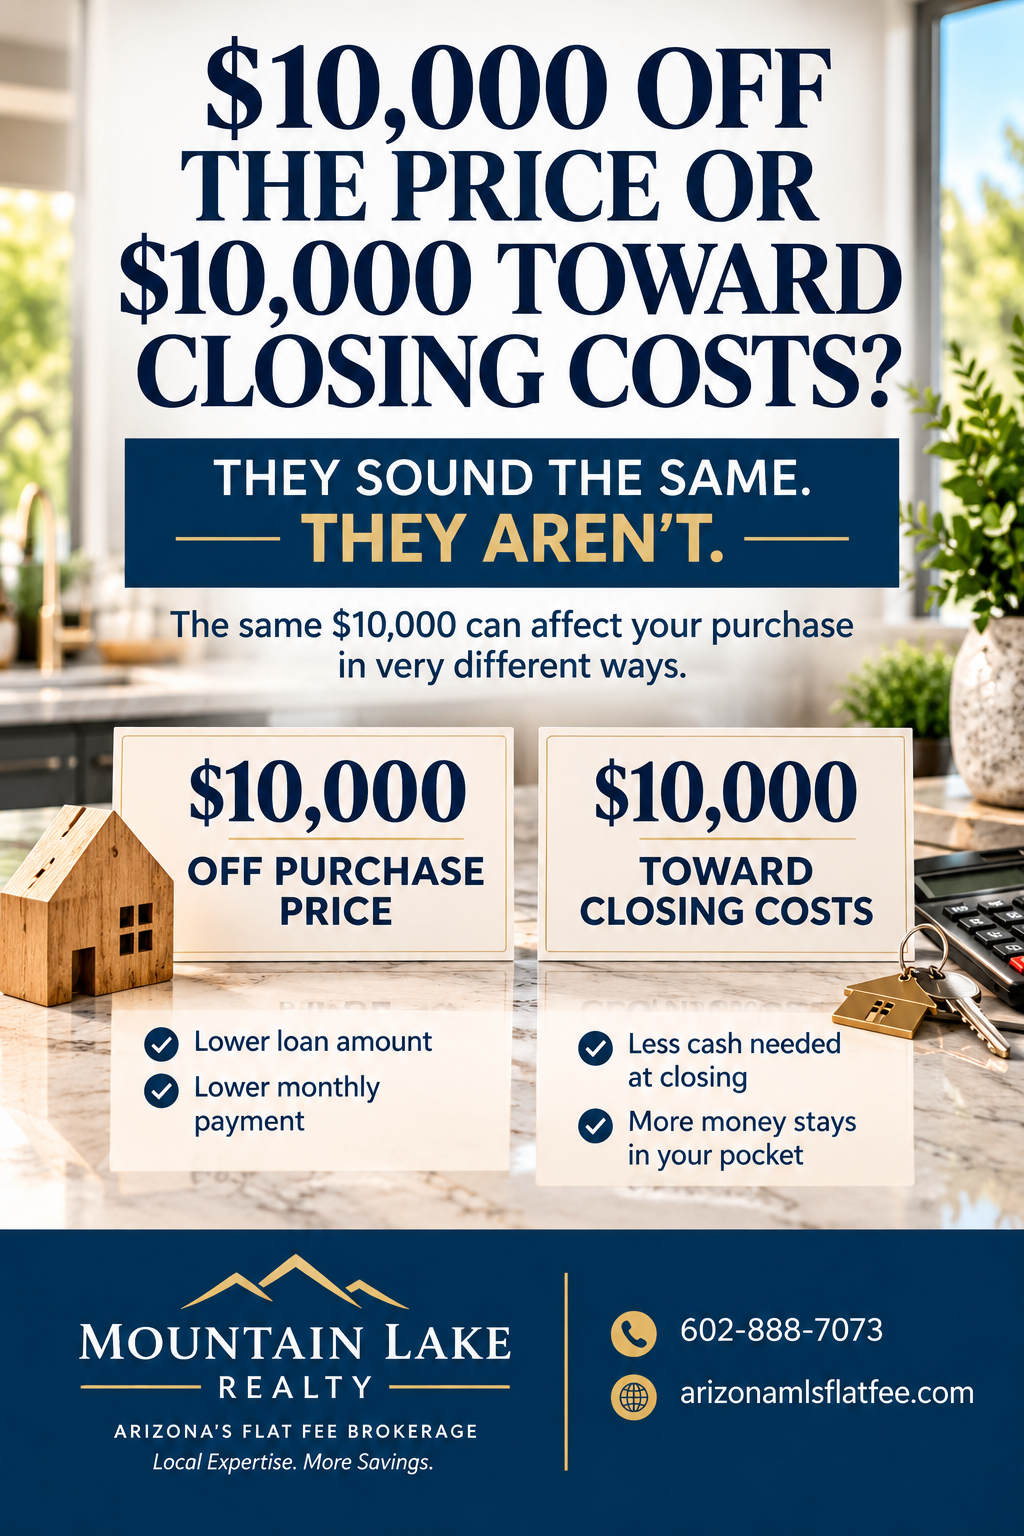
When buying a home, a $10,000 seller concession can sound the same whether it reduces the purchase price or covers your closing costs.
They sound the same. They aren't.
For Arizona homebuyers, understanding the difference between $10,000 off the purchase price and $10,000 toward closing costs can help you determine which option provides the greater financial benefit — and that difference can be significant depending on your situation.
$10,000 Off the Purchase Price
Suppose a home is listed for $500,000 and the seller agrees to reduce the price by $10,000. Your new purchase price becomes $490,000.
The immediate advantage is that you are borrowing against a lower purchase price. With a conventional mortgage requiring 20% down, here is how the numbers change:
Original price: $500,000
- 20% down payment: $100,000
- Mortgage: $400,000
With a $10,000 price reduction:
- New price: $490,000
- 20% down payment: $98,000
- Mortgage: $392,000
That means you need $2,000 less for the down payment and finance $8,000 less. A lower loan balance also means a slightly lower monthly mortgage payment over the life of the loan.
But here is the important consideration: a $10,000 price reduction does not put $10,000 of cash back in your pocket at closing. The savings show up in the lower purchase price, lower loan amount, and potentially lower monthly payment — not as cash you keep.
$10,000 Toward Closing Costs
Now consider the same $500,000 home where the seller agrees to provide a $10,000 credit toward your allowable closing costs. The purchase price stays at $500,000 — but you may use the seller credit toward eligible expenses associated with the purchase, subject to your mortgage program, lender rules, and applicable limits.
Depending on your situation, those expenses could include:
- Loan origination and processing costs
- Title and escrow expenses
- Prepaid property taxes
- Homeowner's insurance
- Other allowable closing expenses
The major advantage is cash preservation. Instead of bringing as much money to the closing table, you may be able to use the seller contribution to cover eligible costs — keeping more of your own money in your pocket.
Which Is Better: Price Reduction or Closing-Cost Credit?
There is no universal answer. The better option depends entirely on your financial situation.
A $10,000 price reduction may make more sense if:
- You want a lower purchase price on paper
- You want to reduce your mortgage balance
- You want a slightly lower monthly payment
- You have sufficient cash available for closing
- Your primary goal is reducing the long-term loan amount
A $10,000 closing-cost credit may make more sense if:
- You want to preserve cash at closing
- You have enough for your down payment but need help with closing expenses
- You want to reduce the amount of money required at the closing table
- You have allowable closing costs that can absorb the full credit
The Difference Can Be Bigger Than It Looks
This is why buyers should not automatically assume that $10,000 is $10,000, regardless of how it is structured.
Consider two buyers purchasing the same $500,000 Arizona home:
Buyer A negotiates $10,000 off the purchase price. They get a lower loan balance and a slightly lower monthly payment.
Buyer B negotiates $10,000 toward allowable closing costs. They retain thousands of dollars that otherwise would have been needed at the closing table.
The right choice depends on your loan type, down payment, available cash, closing costs, interest rate, and long-term plans. Neither option is automatically better — it comes down to your numbers.
What About Using a Concession for a Rate Buydown?
There is a third possibility worth considering. Instead of simply reducing the purchase price or paying closing costs, a seller concession may sometimes be structured to help with an interest-rate buydown, depending on the loan program and lender requirements.
For example, a temporary rate buydown could reduce your mortgage payment during the early years of the loan. However, buyers should compare the actual numbers rather than assuming a rate buydown is automatically the best use of a concession.
Ask your lender to show you the full picture:
- Monthly payment under each scenario
- Total interest paid over the loan term
- Loan balance at key milestones
- Cash required at closing
- Cost of the buydown versus long-term savings
Important: Seller Credits Have Rules
Buyers cannot always receive a $10,000 seller credit simply because the seller agrees to it. Mortgage programs and lenders have rules governing seller concessions and allowable closing costs.
The amount that can be credited depends on factors including:
- The type of mortgage (conventional, FHA, VA, USDA)
- Your down payment percentage
- Occupancy type
- Other transaction details
Also, a seller credit generally cannot be converted into cash back to the buyer beyond what is permitted under the applicable loan rules. That is why you should have your lender and escrow/title company confirm exactly how a proposed seller concession can be used before you negotiate the final terms.
Don't Focus Only on the Purchase Price
When negotiating an Arizona home purchase, buyers sometimes focus entirely on the sales price. But the better question is often:
"What structure gives me the greatest financial benefit given my specific situation?"
A $10,000 reduction in price and a $10,000 contribution toward allowable closing costs may have very different effects on your finances. One reduces the amount you finance. The other reduces the amount of cash you need at closing.
And depending on your circumstances, preserving cash at closing may be far more valuable than shaving a few dollars off your monthly payment.
Talk to your lender, run both scenarios with real numbers, and make the decision that actually works best for you — not just the one that sounds bigger.
What Arizona sellers should know about concession strategy
Understanding how concessions work from the seller's side can help you negotiate more effectively.
When a concession is better than a price reduction
In a balanced market, buyers often ask for seller concessions rather than price reductions. Here is why that can work in your favor as a seller:
A $10,000 price reduction reduces your sale price — and potentially your appraised value — permanently. A $10,000 closing cost contribution keeps the purchase price intact, which can be better for the appraisal and for your net proceeds calculation.
For example, if a buyer asks for $10,000 toward closing costs on a $450,000 home:
- Your sale price remains $450,000
- The appraisal is based on $450,000
- Your net proceeds are reduced by $10,000 (the concession)
If instead you reduce the price to $440,000:
- Your sale price is $440,000
- The appraisal is based on $440,000
- Your net proceeds are reduced by $10,000 (the price reduction)
The net proceeds impact is similar, but the price reduction also affects the appraised value, which can matter if you are in a neighborhood where comparable sales are important.
Concession limits by loan type
Not all concessions are equal. Mortgage programs have limits on how much a seller can contribute toward a buyer's closing costs:
- Conventional loans (less than 10% down): Up to 3% of the purchase price
- Conventional loans (10–25% down): Up to 6% of the purchase price
- FHA loans: Up to 6% of the purchase price
- VA loans: Up to 4% of the purchase price (plus certain fees)
- Cash purchases: No lender-imposed limits
If a buyer asks for a concession that exceeds their loan program's limit, the excess cannot be applied to closing costs. Your broker and the buyer's lender should confirm the allowable amount before you agree to a specific concession.
Rate buydowns as an alternative
Instead of a price reduction or closing cost credit, some sellers offer to fund a temporary interest rate buydown. A 2-1 buydown, for example, reduces the buyer's interest rate by 2% in year one and 1% in year two, then returns to the note rate in year three.
The cost of a 2-1 buydown is typically 2–3% of the loan amount. On a $400,000 loan, that is $8,000–$12,000. The buyer gets lower payments in the early years of the loan, which can make the home more affordable and help them qualify.
Whether a buydown makes more sense than a price reduction or closing cost credit depends on the buyer's specific situation. Ask your broker to model both scenarios with real numbers before deciding.
How to use this knowledge when selling your Arizona home
As a seller, understanding how concessions work helps you negotiate more effectively:
Evaluate concession requests in context. A buyer asking for $8,000 toward closing costs is not necessarily asking for $8,000 off the price. Evaluate the full offer — price, financing, contingencies, and concessions — before deciding how to respond.
Counter strategically. If a buyer asks for a large concession, you can counter with a smaller concession or a different structure. For example, if a buyer asks for $15,000 toward closing costs, you might counter with $8,000 toward closing costs and a $5,000 price reduction — a total of $13,000 in value, structured differently.
Know your bottom line. Before you receive an offer, decide what your minimum net proceeds are. That helps you evaluate concession requests quickly and respond with confidence.
Explore Topics
Written by
Dash List Team at Mountain Lake Realty
Content creator and writer sharing insights and stories.