3-2-1 Buydown Arizona: How Home Buyers Can Lower Mortgage Payments
A 3-2-1 mortgage buydown can give Arizona home buyers a way to reduce their mortgage payments during the first three years of a loan. Here is what you need to know.
A 3-2-1 mortgage buydown can give Arizona home buyers a way to reduce their mortgage payments during the first three years of a home loan. With mortgage rates still affecting affordability, buyers in Phoenix, Scottsdale, Mesa, Chandler, Gilbert, Tucson and other Arizona communities are looking at creative financing strategies that can make purchasing a home more manageable.
A 3-2-1 buydown doesn't permanently lower the mortgage interest rate. Instead, it temporarily reduces the effective interest rate used to calculate the buyer's payments during the first three years.
What Is a 3-2-1 Buydown?
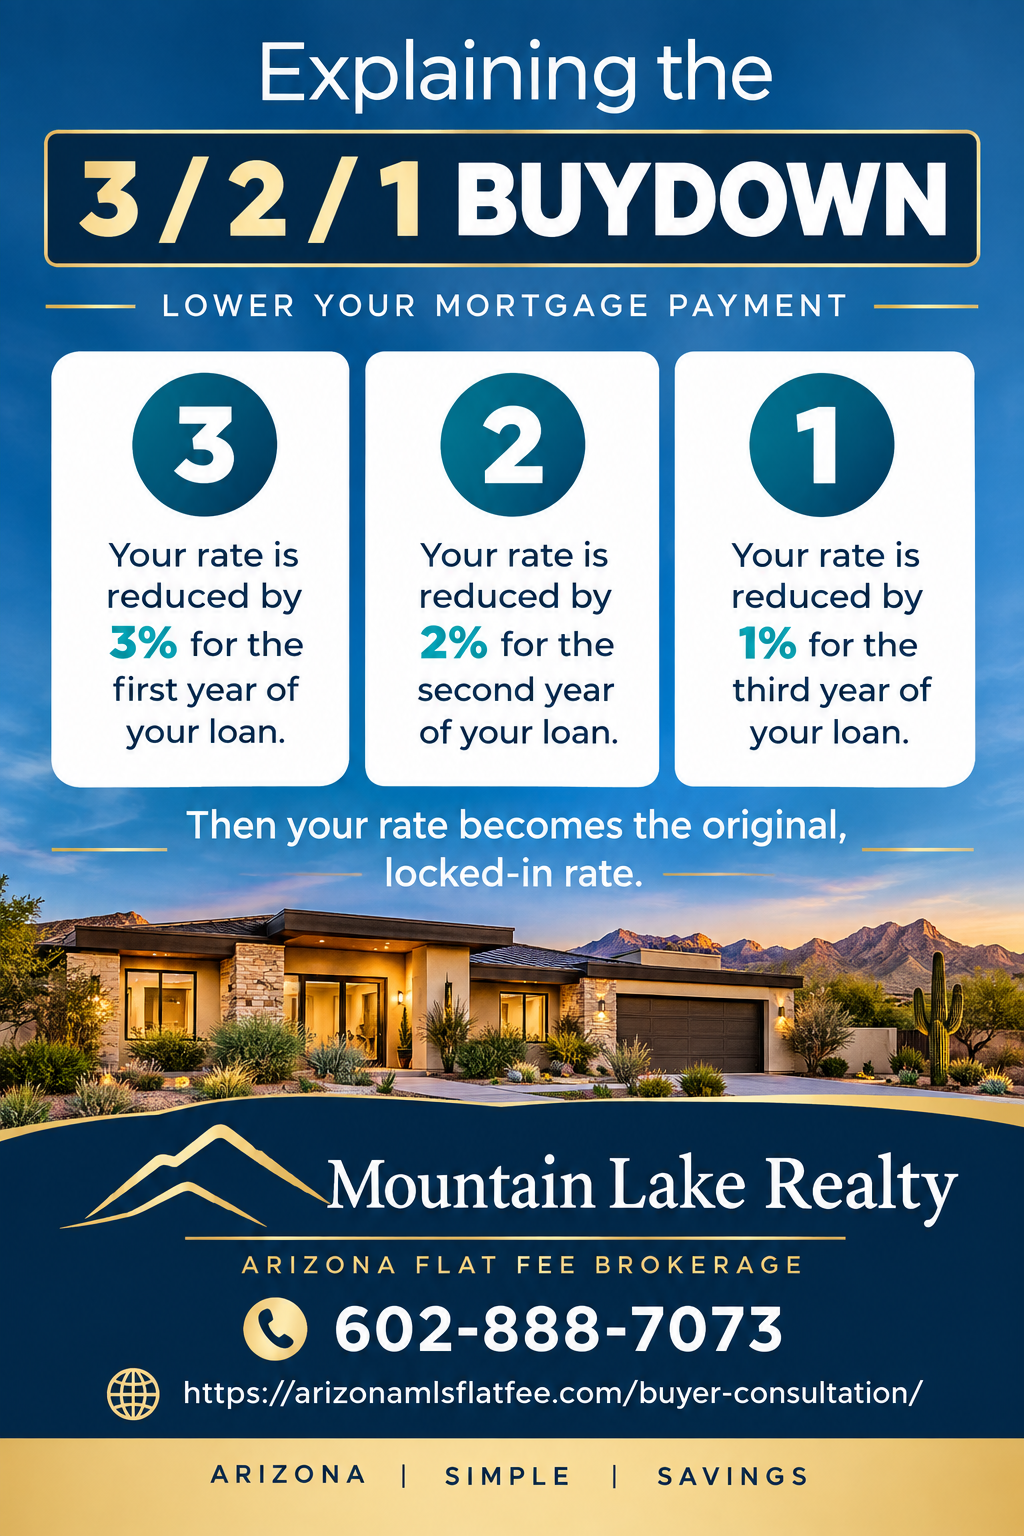
A 3-2-1 mortgage buydown temporarily reduces the mortgage interest rate by three percentage points in the first year, two percentage points in the second year and one percentage point in the third year.
After that, the mortgage returns to its permanent note rate.
For example, if a buyer has a mortgage with a permanent rate of 6.75%, the payment schedule could be based approximately on:
| Year | Temporary Rate |
|---|---|
| Year 1 | 3.75% |
| Year 2 | 4.75% |
| Year 3 | 5.75% |
| Year 4+ | 6.75% |
The actual payment depends on the loan amount, loan program, taxes, insurance and other factors.
The Important Point
The 3-2-1 buydown does not mean the buyer permanently receives a 3.75% mortgage rate in this example. The permanent mortgage rate remains 6.75%.
That's why buyers should make sure they can afford the payment that begins in Year 4.
How Does a 3-2-1 Buydown Work?
Money is placed into an account to subsidize the buyer's mortgage payments during the temporary buydown period.
The cost of the buydown can potentially be paid by an eligible source such as:
- The home seller
- A home builder
- The buyer
- Another permitted party
- A combination of permitted sources
The exact rules depend on the mortgage program and lender.
For an Arizona home buyer, the seller may sometimes agree to contribute toward a temporary buydown as part of the purchase negotiations.
Can an Arizona Seller Pay for a 3-2-1 Buydown?
Potentially, yes.
A seller concession may be negotiated as part of an Arizona real estate transaction, subject to the buyer's loan program, lender requirements and applicable limits.
This can create another negotiating option. Instead of simply asking the seller to reduce the purchase price, a buyer might ask whether the seller would consider an eligible concession toward a mortgage buydown.
For example:
- Option A: Negotiate a lower purchase price.
- Option B: Negotiate an eligible seller concession that can be used toward a temporary mortgage buydown.
These two approaches can have different financial consequences, so the buyer should compare the actual numbers with the lender.
3-2-1 Buydown vs. Lower Home Price
A lower purchase price and a temporary mortgage buydown accomplish different things.
A lower purchase price reduces the amount being financed. A 3-2-1 buydown temporarily reduces the mortgage payment during the initial years of the loan.
For some buyers, the lower initial payment may be particularly valuable. For others, reducing the purchase price or obtaining a permanently lower interest rate may make more sense.
There is no single strategy that works for every Arizona buyer.
Why Are Arizona Buyers Looking at 3-2-1 Buydowns?
Affordability is a major consideration when purchasing a home. Even a relatively small change in mortgage rates can significantly affect a buyer's monthly payment, particularly on a larger Arizona home.
A temporary buydown can give a buyer several years of lower payments. That can be particularly relevant to buyers who expect their financial circumstances to change over time.
However, buyers should not assume that mortgage rates will fall or that they will automatically be able to refinance later. A 3-2-1 buydown should be evaluated using the permanent mortgage payment.
3-2-1 Buydown Example for an Arizona Home
Consider a hypothetical Arizona home purchased with a mortgage carrying a permanent interest rate of 6.75%. The temporary payment structure could look approximately like this:
- Year 1: 3.75%
- Year 2: 4.75%
- Year 3: 5.75%
- Year 4 and afterward: 6.75%
The lower initial payment can provide temporary payment relief. But the buyer needs to qualify for and be comfortable with the permanent payment. The lender can calculate the exact payment difference and the amount required to fund the buydown.
What Happens After the 3-2-1 Buydown Ends?
This is perhaps the most important question.
After the three-year period ends, the mortgage payment is based on the permanent mortgage rate. The buyer should therefore evaluate the home based on the Year 4 payment, not the Year 1 payment.
If the permanent payment is affordable, the temporary reduction can provide additional flexibility during the first three years.
Should You Use a 3-2-1 Buydown When Buying a Home in Phoenix?
A 3-2-1 buydown may be worth discussing with a lender if you're purchasing a home in Phoenix, Scottsdale, Mesa, Chandler, Gilbert, Glendale, Peoria, Surprise, Goodyear, Buckeye, Queen Creek or another Arizona market.
The key is to compare the numbers. Ask your lender to provide:
- The permanent mortgage rate
- The Year 1 payment
- The Year 2 payment
- The Year 3 payment
- The Year 4 payment
- The total cost of the buydown
- The source of the buydown funds
- Any applicable contribution limits
- What happens to unused funds if the mortgage is paid off early
Can a 3-2-1 Buydown Help You Buy Now?
For some buyers, the biggest question isn't whether mortgage rates could eventually decline. It's whether they can comfortably purchase a home today.
A temporary mortgage buydown can potentially reduce the initial payment and give the buyer time to adjust to the permanent payment. But buying a home is a long-term financial decision.
Buyers should avoid purchasing a home solely because the first-year mortgage payment looks attractive. The permanent payment, purchase price, cash requirements, property taxes, insurance, HOA costs and overall budget all matter.
3-2-1 Buydown FAQs
What is a 3-2-1 mortgage buydown?
A 3-2-1 mortgage buydown temporarily reduces the effective mortgage rate by three percentage points during the first year, two points during the second year and one point during the third year.
Does a 3-2-1 buydown permanently lower my mortgage rate?
No. The mortgage has a permanent note rate. The temporary reduction generally applies only during the first three years.
Can the seller pay for a 3-2-1 buydown?
Depending on the loan program and applicable rules, an eligible seller concession may be used toward a temporary rate buydown.
Is a 3-2-1 buydown available on every mortgage?
No. Availability depends on the loan program, lender requirements and other transaction-specific factors.
What happens in Year 4?
The temporary buydown ends and the payment generally returns to the amount based on the permanent mortgage rate.
Should I wait for mortgage rates to fall?
That is a personal financial decision. Buyers should compare the cost of purchasing now — including the permanent mortgage payment — with the potential costs and benefits of waiting.
3-2-1 Buydown Arizona: The Bottom Line
A 3-2-1 mortgage buydown is one financing strategy Arizona home buyers can consider when mortgage payments are affecting affordability. It can provide temporary payment relief for three years, but it is important to understand exactly what happens after the temporary period ends.
Don't just ask, "What is my payment in Year 1?"
Ask: "What will my payment be in Year 4, and can I comfortably afford it?"
That number should be a central part of the home-buying decision.
Mortgage programs, interest rates, underwriting requirements and allowable seller contributions vary. Consult a qualified mortgage professional for information regarding your specific loan.
Arizona Flat-Fee Real Estate Services
If you're buying or selling an Arizona home, the Dash List Team at Mountain Lake Realty provides Arizona real estate services and flat-fee listing options starting at $59.
📞 (602) 881-8674 | View Buyer Consultation Options
Ready to list your Arizona home?
Dash List Team offers flat fee MLS listing starting at $59 upfront and 0.5% at closing — full MLS exposure, professional photography, Zillow Showcase, and contract support included.
View pricing and packages · How it works · Get a free consultation
Serving sellers across Phoenix, Scottsdale, Tucson, Mesa, Chandler, Gilbert, and all Arizona cities.
Explore Topics
Written by
Dash List Team at Mountain Lake Realty
Content creator and writer sharing insights and stories.